-
14 Sep, 2026
Why Does One Website Keep Growing While a Similar Website Stays Stuck?
Two publishers, same niche, same content category, similar audience targets. Both doubled their monthly sessions over two years. One doubled its revenue. The other grew revenue by less than 20%.The instinct is to look for a difference in SEO, content quality, or monetisation setup. Sometimes one of those is the answer. But often the real difference is simpler and harder to see: they grew different kinds of traffic.Most publishers track growth as a single number. Sessions, users, pageviews. That number goes up and the business is assumed to be growing. But the number does not tell you what changed inside those sessions. And what changed inside them is what advertisers actually pay for.The argument in short• Traffic growth is not one thing. Growth in sessions and growth in session depth have completely different monetisation outcomes.• Impressions per session and impressions per pageview are the strongest predictors of publisher revenue, outperforming fill rate, viewability, and CPM.• Four growth types exist: breadth, depth, frequency, and identity. Only three of them raise the monetisation ceiling.• A publisher can hit every traffic target and still miss revenue targets, because they grew the wrong dimension.• The ad stack built for a breadth-growth site is usually the wrong stack for a depth or identity-growth site.What Growth Actually Consists OfA publisher's traffic can grow in four distinct dimensions, and the analytics dashboard usually shows only the total.Breadth. More sessions, from more people, behaving roughly the same way. A publisher who acquires new visitors from a new source or a new topic is growing breadth. Session count rises, but pages per session and return rate stay flat.Depth. The same visitors consuming more content per visit. A publisher whose internal linking, related content, or site architecture improves will see pages per session rise even if session count stays flat.Frequency. The same visitors returning more often. A publisher whose newsletter, editorial cadence, or brand loyalty improves will see return visits rise without new audience acquisition.Identity. The same visitors becoming known. A publisher who moves anonymous readers into email subscriptions, logged-in accounts, or paid relationships is growing the proportion of its audience that advertisers value most in the post-cookie market.These four dimensions are not interchangeable. Growth in one does not produce the same revenue outcome as growth in another. And the dashboard, which reports them all as "sessions" or "pageviews," does not distinguish between them.Why the Difference MattersPlaywire analysed aggregated ad performance across thousands of publisher websites, covering 8.8 billion sessions, 28.6 billion pageviews, and 113.6 billion ad impressions. The finding that matters most for growth strategy is this: impressions per session (r=0.60) and impressions per pageview (r=0.57) were the two strongest predictors of revenue performance, outperforming fill rate, viewability, CPM, and session duration.Read that against the four growth dimensions. Breadth growth, if it produces more sessions with the same pages per session, does not move the metric that correlates most strongly with revenue. Depth growth does. So does frequency growth, because returning visitors generate more sessions per user, which is a different path to the same underlying variable.This is the mechanism behind the two publishers in the opening scenario. Both doubled sessions. One doubled them by acquiring new first-time visitors who read one page and left. The other doubled them by getting existing readers to come back more often and read more deeply. Both dashboards showed the same headline growth. Only one of those patterns raises the revenue ceiling.The Freestar case study offers a related signal. When the company removed 50% of ad units from one publisher site, revenue fell only 5% while traffic from the publisher's top five sources rose 28%. Revenue later surpassed pre-cleanup levels. That outcome is only possible if the site's audience relationship was strong enough to withstand a reduction in ad friction and reward it with more return visits. The depth and frequency were already there. Removing ads revealed them.The Revenue Premium on the Right Kind of GrowthThe dimensions that raise monetisation do not just produce more impressions. They produce more valuable ones.Direct traffic is the clearest example. News Corp has reported that direct traffic is ten times more valuable to advertisers than social traffic and five times more valuable than search. Direct visitors have chosen the brand, remember the domain, and are more likely to be in a session that continues. A publisher growing direct traffic is growing frequency and identity simultaneously, and the CPM premium reflects that.Authenticated audiences are the second. The Reuters Institute's Digital News Report found that 79% of news publishers now rate first-party data strategy as a top three priority. That number reflects a real valuation shift. In a market where third-party identifiers have eroded, publishers who can offer verified, consented audience segments command premium CPMs that anonymous traffic cannot match. Identity growth is not a branding exercise. It is an inventory upgrade.Both premiums exist because advertisers pay for what they can measure and trust. A direct visitor who returns weekly is a measurable relationship. An authenticated reader is a known audience member. A first-time visitor from a social referral is neither. The two publishers in the opening scenario may have had the same traffic number, but they did not have the same inventory.What Breadth Growth Does to MonetisationBreadth growth is not bad. It is necessary. Every publisher needs to keep acquiring new readers, and a site that stops doing so eventually shrinks.The problem is that breadth growth alone does not lift the monetisation ceiling. It adds sessions without changing the underlying composition of the audience. If new visitors behave like the existing first-time visitors, the site's overall revenue-per-session stays roughly constant. Sessions double, revenue doubles, and the publisher has grown linearly rather than compounding.Worse, breadth growth can dilute. If the new audience arrives from a source with lower commercial value than the existing audience, the blended average CPM can fall even as traffic rises. A publisher who adds 500,000 sessions from a low-value geography or a low-intent channel has grown the traffic number and moved the revenue number in the wrong direction.This is the specific pattern behind many publishers who report strong traffic growth and flat revenue. They are not failing at monetisation. They are succeeding at a kind of growth that does not show up in monetisation.Diagnosing Which Growth You Are ProducingThe practical work is separating the four dimensions in your own reporting. Most analytics platforms can surface them with modest configuration.For breadth: sessions and users over time, split by acquisition channel. If growth is concentrated in a new channel while pages per session and return rate stay flat, you are growing breadth.For depth: pages per session and pages per user, tracked over time. If these are rising, internal linking and content architecture are working. If they are flat while sessions rise, the new traffic is not going deeper.For frequency: return visitor rate and sessions per user. Direct traffic share is a useful proxy. If direct share is flat or declining while total sessions rise, the new audience is not converting to familiarity.For identity: newsletter subscribers, logged-in users, and paying subscribers as a percentage of total audience. If this ratio is falling while traffic rises, the publisher is adding anonymous visits faster than known relationships.The diagnostic question is not whether each metric is growing. It is whether the mix is shifting toward the dimensions that raise monetisation or away from them. A publisher can have growing traffic and shrinking monetisation capability at the same time, if the growth is concentrated in the wrong dimension.The Ad Stack Question This CreatesPublishers who diagnose this pattern often discover a second problem downstream. The ad stack was built for the site they used to be.A breadth-growth publisher running a high-volume, low-CPM setup is a reasonable configuration. Efficiency comes from scale, floors are set to maintain fill, and the formats are tuned for a first-time visitor who will read one page and leave. There is nothing wrong with that stack for that audience.A depth-and-identity publisher needs something different. Depth audiences read further, so the ad density appropriate for a two-page session is wrong for a six-page session. Identity audiences justify premium floor prices, because advertisers will pay more for known readers. Frequency audiences produce the return visits that command the direct traffic premium, and the floor logic should reflect that.When the growth composition has shifted but the ad stack has not, the publisher has two problems layered on top of each other. The traffic is not producing the revenue it should, and the setup is not capable of capturing what the traffic has become.This is where the partner question becomes concrete rather than rhetorical. If a publisher has grown depth, frequency, and identity, and their revenue has not tracked, the diagnosis is usually not a tuning problem. It is a demand-side gap: the current stack is not exposing the site's premium inventory to buyers who would pay for it. Testing a second demand source against the highest-value segment is the cleanest way to find out whether the ceiling is the market or the current setup.Publishers who have genuinely grown the valuable dimensions of their traffic often find that the gap is not on the demand side at all. It is that the current stack was never built for the audience the site has become. Adstork works with established publishers in exactly that position, usually as a second demand source tested against specific high-value segments rather than a wholesale replacement. You can request a segment-level review here if the pattern in this article looks familiar and you want an external view on where the gap sits.What This Changes About Growth StrategyMost publishers set growth targets in a single number. Ten million sessions by the end of the year. Fifty percent more users. Another million pageviews per month. These targets are easy to track and easy to communicate, and they are almost always the wrong target.A publisher who hits ten million sessions by growing breadth alone has achieved the number and missed the business. A publisher who hits seven million sessions by growing depth, frequency, and identity has achieved something more valuable, and their revenue will show it.The practical shift is to set targets in the dimensions that matter. Growth in pages per session. Growth in return rate. Growth in direct share. Growth in authenticated audience. These are harder to move than session count, and they compound in a way that session count does not.Two publishers can start in the same niche, publish similar content, and target the same readers. If one grows breadth and the other grows depth, frequency, and identity, they will not end up with the same business. The traffic numbers may look similar for a while. The revenue will not. And by the time the gap is obvious in the reporting, the underlying cause will be years in the past.FAQsWhy does my traffic keep growing but my revenue does not? The most common cause is that growth is concentrated in breadth, meaning more sessions from new visitors behaving like existing first-time visitors, rather than in depth, frequency, or identity. Playwire's ecosystem analysis found that impressions per session and impressions per pageview are the strongest predictors of revenue, so growth that does not move those metrics will not move revenue proportionally. Diagnose which dimension is growing before assuming the problem is in monetisation.Is direct traffic really worth more than search or social? Yes, and by a wide margin. News Corp has reported that direct traffic is ten times more valuable to advertisers than social and five times more valuable than search. The premium reflects what direct visitors signal: brand familiarity, higher trust, and a greater likelihood of being in a session that continues. A publisher whose direct share is growing is not just growing traffic. They are growing the composition of their audience in a way that advertisers pay for.Should I change ad partners if my growth has shifted toward depth and identity? Only after confirming the diagnosis. A depth-and-identity publisher with a flat revenue line has two possible problems: the ad stack is configured for a breadth-growth site, or the demand stack is not exposing the premium inventory to buyers who would pay for it. The first is a tuning problem. The second is a partner question. Test a second demand source against the highest-value segment and compare revenue per session, not headline CPM. The result will tell you which problem you actually have.
Read More
-
10 Sep, 2026
Why Publisher Growth Can Create New Monetization Problems.
Growth is supposed to solve problems. More traffic means more inventory. More inventory means more revenue. The ad settings that worked at two million pageviews should work even better at twenty million.Then a publisher scales, and something unexpected happens. Revenue does not grow at the rate traffic did. And the explanations that used to work, whether floor prices, fill rates, or SSP coverage, stop explaining anything.The reason is that growth does not just scale the business. It changes the category of problem the business has to solve.A publisher who outgrows a configuration has a tuning problem. A publisher who outgrows a capability has a business problem. The two require completely different responses, and confusing them is why so many growing publishers spend a year swapping partners without fixing anything.The Difference That MattersConfiguration problems respond to settings. Stale floor prices, mismatched SSP coverage, ad density calibrated for last year's device split: these are all fixable internally, and they are covered elsewhere. They do not require a new partner, a new hire, or a new contract.Capability problems do not respond to settings. They require someone to own a new responsibility, monitor a new risk, or renegotiate a commitment. Adjusting a floor price does not fix them. Adding an SSP does not fix them. Swapping networks does not fix them.Four categories of capability problem appear after growth. Most publishers notice them as symptoms, like revenue that plateaus despite traffic growth or deals that used to work fine that now seem restrictive. Very few diagnose them correctly.A Publisher at Three Million and the Same Publisher at FifteenAt three million monthly pageviews, one person handles monetisation. They manage the Google Ad Manager account, the SSP relationships, the floor prices, the ad placements, and the monthly reporting. It is a full-time job, but it is a job one person can hold in their head.At fifteen million, that person is now the bottleneck for everything. Direct advertiser conversations started arriving. A premium brand wants a private marketplace deal. Someone needs to review the ads.txt file weekly because inventory hijacking attempts have started appearing. None of that work fits into the original job description, because the original job description was written for a smaller business.Nothing here is a settings problem. Floor prices could be perfectly calibrated. The SSP stack could be exactly right. The business still has a monetisation problem, because the problems it now has are not the problems its tools were built to solve.Category One: Adversarial AttentionFraud does not target small sites. It targets sites worth impersonating.Pixalate's Q2 2026 data puts global invalid traffic at roughly 20% for web, 41% for mobile app, and 26% for CTV. Those are ecosystem averages, and the distribution is not even. Larger, better-known domains are more valuable to spoof because buyers are more likely to bid on them without scrutiny.Two patterns specifically target growing publishers. The first is ads.txt hijacking, where fraud operators clone a publisher's authorised seller file and route fake inventory through legitimate-looking supply paths. The publisher's brand appears in the bid request while impressions are served elsewhere. The second is AI content farms that copy established publishers' ads.txt files to hijack attribution.Both problems get worse with scale, not better. A three-million-pageview site is not worth impersonating. A fifteen-million-pageview site is. And the consequence is not just lost revenue. Buyers associate the publisher's domain with fraud signals, and the domain gets quietly filtered out of premium auctions.This requires monitoring, not adjustment. Someone has to review the ads.txt file, watch for unauthorised resellers, and respond when a DSP flags the domain. That is a job, and at smaller scale it did not exist.Category Two: The Yield GapThere is a specific moment when yield stops being anyone's job. It happens quietly, usually between five and ten million monthly pageviews.Before that point, one person does everything and naturally does yield management as part of the role. After that point, the work splits. Editorial takes content, product takes the site, ad ops takes delivery. Yield management, the practice of continuously optimising floor prices, demand mix, and format allocation against market conditions, falls between the roles. Nobody was assigned it. Nobody noticed it was missing.The symptom does not look like neglect. It looks like a site whose revenue grows in proportion with traffic but never outperforms it. The floors are set at last year's levels. The SSP stack is the one assembled two years ago. The format mix reflects the device split the site had before mobile became the majority. Every individual component is defensible. Nobody is responsible for the combination.Category Three: Contractual Lock-InDeals negotiated at smaller scale become constraints at larger scale. This is structural, not a negotiating failure.A publisher at three million pageviews signs a twelve-month agreement with an SSP that includes a revenue share and an exclusivity clause on certain formats. At three million, that deal was reasonable. It brought demand the publisher could not access alone, and the exclusivity cost was small because the site did not have much premium inventory to place elsewhere.At fifteen million, the same exclusivity clause blocks the publisher from testing formats that have since become the most valuable part of its inventory. The deal that enabled growth now prevents the publisher from monetising what growth produced.The same pattern appears with direct advertiser commitments. A brand that bought guaranteed inventory when the site was smaller can lock up premium placements that would now command significantly higher rates in the open market. The publisher is honouring a deal at last year's price while the market has moved.None of this is corrected by changing ad settings. It requires contract review, and it requires publishers to think about commitment terms in terms of the scale they expect to be at when the contract ends, not the scale they are at when it is signed.Category Four: Channel ConflictAt smaller scale, direct sales and programmatic do not compete. There is not enough premium inventory for direct sales to matter, so most of the site runs through the open market and everyone is happy.At larger scale, they compete directly. The same premium placements can be sold to a direct advertiser at a fixed CPM or released into the programmatic auction where they may clear higher. The sales team wants inventory committed. The programmatic team wants flexibility. Neither is wrong, and the conflict is real.Most publishers resolve this badly at first. They either over-commit to direct deals and leave upside on the table, or they under-commit and lose the premium brand relationships that take years to build. Getting the balance right requires a view of what each placement is worth across both channels, which in turn requires reporting most smaller publishers have never had.What to Do About ItThe response is not to rebuild everything. It is to separate the problems by category and assign each one to the right fix.Configuration problems respond to tuning. These are covered elsewhere and they can be corrected internally.Capability problems require assigning responsibility. Someone has to own each one. This is usually the harder fix, because it means hiring, restructuring, or outsourcing, and it does not produce an immediate revenue bump.Partner problems (demand access, support level, format coverage at current scale) respond to market testing, but only after the first two categories have been addressed. A new partner cannot fix a problem that is internal.The sequence matters. Publishers who test new partners before diagnosing which category their problem belongs to end up churning through relationships without understanding why none of them fixed anything.Most publishers who reach this stage do not need to replace anything. They need a second source of demand that operates at the scale they have become, and a partner who will look at their specific inventory rather than their account tier. Adstork works with publishers in that position, usually as an additional demand source tested alongside what already works, and usually with a conversation about the inventory before any conversation about the integration. You can start that conversation here if the problems above sound familiar.Growth is not the problem. Growth is the thing that revealed it. The publishers who handle it well notice which category they are in before they start solving.Two Questions Publishers AskHow do I know whether my problem is a configuration issue or a capability issue? Ask whether a settings change would fix it. If the answer is yes, it is configuration. If the answer is that someone would have to own a new responsibility, monitor a new risk, or renegotiate a commitment, it is a capability problem. The second category does not respond to tuning.At what size do these problems typically appear? Adversarial attention starts becoming a real risk somewhere above five million monthly pageviews and accelerates from there. The yield ownership gap usually appears between five and ten million. Contractual lock-in depends on what was signed and when, not on scale alone. Channel conflict appears once direct sales becomes a meaningful share of revenue, which varies by vertical.
Read More
-
11 Sep, 2026
When Should Publishers Treat Different Parts of Their Website Differently?
A publisher with 40,000 pages is running one monetisation strategy. One set of floor prices. One ad density. One SSP configuration. One format mix. The strategy is either right for most of those pages or wrong for most of those pages. It is almost never both.This is not a tuning problem. It is a modelling problem. The publisher has treated a collection of different products as though they were one, because they happen to share a domain.Understanding when that assumption holds and when it breaks is one of the more consequential decisions an established publisher makes. Not because uniform strategies are inherently wrong, but because the circumstances in which they are right are narrower than most publishers assume.The argument in short• A domain is an address, not a product. The product is the impression, and impressions differ enormously across a site.• Four dimensions determine whether pages deserve different treatment: user intent, session position, content format, and user state.• The cost of treating them uniformly is not just suboptimal revenue. It is that the highest-value inventory effectively subsidises the rest.• Segmentation has diminishing returns. Most established publishers can manage four to six page archetypes, not forty.• Once segmentation is the diagnosis, the partner question becomes whether the current demand stack can serve more than one inventory profile.Why Uniform Monetisation Is the DefaultThe default is uniform for good reasons. Most ad technology is designed to be deployed sitewide. A Google Ad Manager tag fires on every page. SSP integrations apply globally. Floor prices are set at the account level and cascade down unless someone intervenes. Ad density is often defined by a template, and templates are shared across content types.Uniform treatment is also easier to manage. One set of numbers to monitor. One explanation when something goes wrong. One report the sales team can read without a glossary. Publishers who have tried segmentation and abandoned it usually did so for operational reasons, not strategic ones.The problem is that uniform treatment implicitly assumes the site is one product. On a small site, that assumption is close enough to true. On an established site, it usually is not.Four Dimensions Where Pages Actually DifferThe differences between page types on the same site are not cosmetic. They change the value of the impression, the appropriate ad density, and the kind of demand that will respond.User intent. A reader on a buying guide is in a materially different state from a reader on a breaking news article. One is researching a purchase, the other is consuming information. Advertisers pay for the first and tolerate the second. In practice, this means commercial-intent pages often command significantly higher CPMs than editorial pages in the same vertical, but publishers who run the same floor prices across both are leaving that difference uncaptured.Session position. The first pageview of a session is a different product from the fifth. A reader who has arrived from search, found what they needed, and moved on is different from a reader who has navigated four pages deep into the site. Return visitors are different again. News Corp has reported that direct traffic is ten times more valuable to advertisers than social traffic and five times more valuable than search. That gap is not just about traffic source. It is about what direct visitors signal: familiarity with the brand, higher trust, and greater likelihood of being in a session that continues.Playwire's ecosystem analysis reinforces the point. Across thousands of publisher sites, impressions per session (r=0.60) and impressions per pageview (r=0.57) were the two strongest predictors of revenue performance, outperforming fill rate, viewability, CPM, and session duration. The strongest lever is not what an individual ad earns. It is how many ad opportunities a session produces, which is fundamentally about which pages a reader visits and in what order.Content format. A 3,000-word analysis supports a different ad density than a 300-word news brief. A category archive behaves differently from an article. A tool or calculator page has different session dynamics than either. Ad density that is appropriate on long-form editorial may be excessive on short news, and insufficient on evergreen resource pages where readers scroll further and stay longer.The Lumen Research study with Mail Metro Media offers one data point on this. Reducing a simulated page from 15 ads to five lifted the share of readers who viewed an ad from 53% to 78%, with 4.2x higher spontaneous recall and an 8% lift in purchase intent. Fifteen ads was clearly too many. But five ads might be too few on a page with three times the dwell time, and considerably too many on a page a reader glances at for fifteen seconds.User state. Anonymous visitors, authenticated readers, email subscribers, and paying subscribers are four different audiences. The Reuters Institute's 2025 Digital News Report found that 79% of news publishers now rate first-party data strategy as a top three priority. That priority reflects a real valuation difference. Publishers who have built authenticated audiences hold inventory that commands a premium in the post-cookie market. Serving that inventory through the same floor prices and demand stack as anonymous traffic undercuts the asset.What This Actually Looks Like in PracticeConsider a mid-sized publisher with four clearly distinct page categories: news articles, evergreen how-to guides, category archive pages, and newsletter landing pages.The news articles are short, updated frequently, and mostly read by first-time or low-frequency visitors arriving from search and social. Session time is brief. Dwell time is brief. Many readers never scroll past the fold.The how-to guides are long, evergreen, and mostly found by search. Readers arrive with a specific task in mind and stay longer. They scroll. They click related guides. They return.The category archives are navigation, not content. They serve readers who are exploring a topic. Their value is in the session they initiate, not the time spent on the page itself.The newsletter landing pages convert anonymous traffic into authenticated traffic. Their advertising value is low, because the reader is there to complete a specific action. Their strategic value is high, because they generate the authenticated audience that improves monetisation everywhere else.A uniform strategy treats all four identically. Every page gets the same density, the same formats, the same floors, and the same demand stack. The how-to guides end up under-monetised relative to their dwell time and reader quality. The news articles end up over-monetised relative to their attention economy, which damages the reader relationship and suppresses viewability. The category pages contribute negligible value despite anchoring the sessions that produce the site's most valuable impressions. The newsletter landing pages compete with advertising for the reader's attention at exactly the moment the publisher should not be selling it.None of these pages is being badly managed in isolation. The failure is in treating them as interchangeable.How to Decide Where Uniform Treatment Still Makes SenseNot every site needs segmentation. Uniform monetisation remains correct when three conditions hold.First, page types are genuinely similar in intent, format, and reader state. A site that publishes one kind of content to one kind of audience can often run one strategy without loss.Second, the operational cost of segmentation is not worth the return. Managing four or five archetypes requires additional reporting, additional floor logic, and additional attention. On smaller sites, the effort often exceeds the gain.Third, the site's reporting can actually support it. If you cannot see performance by page type, page depth, or session position, you cannot manage segmentation. Many publishers attempt it and fail because the data does not support the decision.When these conditions hold, uniform treatment is efficient. When any of them breaks, uniform treatment becomes a modelling error that quietly suppresses revenue.The Practical Limit on SegmentationIt is tempting to respond to this argument by segmenting everything. That approach fails for predictable reasons.Publishers who try to manage forty page types end up with forty sets of stale assumptions. Floor prices are set and forgotten. Reporting becomes unreadable. The sales team cannot explain the site's inventory to buyers. The operational overhead consumes the analyst time that would have produced the gains.The workable target for most established publishers is four to six archetypes. These should map to the site's actual differentiators, not to a theoretical taxonomy. Useful archetype groupings tend to be:• High-intent commercial pages (buying guides, product reviews, comparison content)• Editorial content (news, features, analysis)• Evergreen or reference content (how-to guides, tutorials, resource pages)• Utility and navigation pages (category archives, tag pages, search results)• Acquisition pages (newsletter signup, subscription, account creation)• Authenticated content (subscriber-only or logged-in experiences)Not every site needs all six. Most sites have two or three that clearly matter and two or three that can be grouped together. The exercise is less about the taxonomy and more about the discipline of asking, for each archetype, whether the current setup reflects the value of the inventory being served.What Changes When You SegmentThree things typically change once a publisher segments its inventory by archetype.Floor prices differentiate. Commercial-intent pages can justify materially higher floors than editorial. Category pages may benefit from lower floors that maintain high fill rates for session-initiating inventory. Newsletter landing pages may benefit from no advertising at all.Ad density calibrates to dwell time and scroll depth rather than to a shared template. Long-form content supports more placements than short news. Utility pages support fewer than either. Density becomes a decision about each archetype rather than a sitewide default.Format mix reflects what each page type actually produces. Video performs differently on evergreen content than on news. Native formats fit editorial contexts better than they fit commercial-intent pages. Sticky units behave differently on mobile than desktop. Segmenting by archetype makes format decisions concrete rather than theoretical.The result is not dramatically more complexity. It is a smaller number of decisions, each made with better information, replacing a single decision that was being applied to situations where it did not fit.The Partner Question This CreatesOnce a publisher accepts that its inventory is not uniform, a different question emerges. Can the current demand stack serve more than one inventory profile well?Many ad networks are built around a single inventory profile. They optimise for a particular content type, a particular geographic mix, or a particular format. On a site with multiple archetypes, these networks typically perform well on some pages and poorly on others. The publisher then faces a choice: accept the mismatch, add partners to cover the gaps, or find a partner whose demand is diversified enough to serve the whole site.This is where the diagnosis becomes actionable. If segmentation reveals that 20% of the site's pages are producing 60% of the revenue (a common pattern once the analysis is run), the question is not how to make the other 80% earn more. It is whether those high-value pages are getting access to the demand that their actual quality justifies, or whether they are being monetised through a stack that was built for the site's average.A second source of demand, tested specifically against the highest-value archetype, is often the fastest way to find out whether the ceiling on those pages is the market or the current setup.Most publishers who run this analysis find that the answer is a mix: some segments improve with tuning, others point to a genuine demand gap that the current stack cannot close. Adstork works with established publishers whose inventory has more than one profile, and who are looking for a second demand source to test against their highest-value segments rather than a replacement for what already works. You can request a segment-level review here if you want a second opinion on which archetypes are being under-served by the current setup.What to Take AwayThe uniform default is not a mistake in itself. It is a reasonable simplification that works well under conditions most publishers outgrow without noticing.The question is not whether to segment. It is whether the pages on your site are still similar enough that treating them identically produces the right outcome. For most established publishers, the honest answer is that some pages have been subsidising others for years, and the pattern has been invisible because the reporting was never built to show it.The diagnostic is simple. Pull performance by page type, session position, and user state. If the numbers cluster tightly, uniform treatment is fine. If they spread widely, the strategy is doing something that the site's inventory did not ask for.Growth makes this problem worse over time, not better. Every new content type, every new geography, every new format adds a different inventory profile that a uniform strategy will not distinguish. Recognising when the uniform assumption stopped fitting is one of the more consequential decisions a growing publisher makes.FAQsHow do I know whether my site actually needs segmentation? Run a segment-level performance report grouped by page type, session position, and user state. If the spread in eCPM, fill rate, and revenue per session is narrow across those dimensions, uniform treatment is fine. If the spread is wide, the site has multiple inventory profiles being served by one strategy, and the highest-value segments are probably being under-monetised.What is a reasonable number of page archetypes to manage? Four to six for most established publishers. Fewer than four and the archetypes probably are not capturing real differences. More than six and the operational overhead starts to outweigh the gains. The right number is the smallest set that separates pages with genuinely different intent, format, or reader state from each other.Should I change ad partners before or after segmenting my inventory? After. Segmentation is a diagnostic. It tells you which pages are under-served and why. Without that diagnosis, evaluating a new partner is guessing. Once segmentation shows a specific demand gap, testing a second source against that specific segment gives you a clean comparison. Testing without the diagnosis usually produces a switch that fixes one segment and breaks another.
Read More
-
10 Sep, 2026
Why Do Publishers Outgrow Their Advertising Strategy?
The dashboard says everything is fine. Fill rate is 82%. eCPM is up 4% year on year. Revenue is growing.That is the problem.When a publisher's advertising strategy stops fitting its business, the symptoms do not look like failure. They look like competence. Revenue grows slowly. Fill rate holds steady. Every metric is measured against last month, and last month was fine too. The mismatch stays hidden because nothing in the reporting compares the current setup against what the current inventory should be capable of.This is what outgrowing an advertising strategy looks like. Not a collapse. A slow divergence between the website a publisher has become and the monetisation system built for the website it used to be.The argument in short• An advertising strategy is a set of assumptions about a business. When the business changes, the assumptions quietly become wrong.• Five dimensions shift as publishers grow: geography, content architecture, traffic source composition, device mix, and authenticated audience.• Each shift changes the type of demand a publisher needs, not just the volume. None of these changes trigger an automatic update to the ad stack.• The mismatch is invisible because dashboards compare against your own history, not against what your current inventory should earn.• Reassessing a strategy is a different exercise from switching a network. Most publishers confuse the two.A Publisher That Grew Into a Different BusinessConsider a composite example. Three years ago, a site had 2 million monthly pageviews, one content vertical, 90% US traffic, and an audience that arrived mostly from search. The ad strategy was set to match: display-heavy, four placements per article, floor prices tuned for US desktop, one primary SSP plus a secondary for backup demand.Today the same site has 8 million monthly pageviews. It has three content verticals. Forty percent of traffic is international. A newsletter with 200,000 subscribers drives a meaningful share of return visits. The audience mix has shifted from search-led to a blend of direct, email, and social. Average article length has doubled. Video appears on a third of pages.The ad strategy is largely the same.Nothing is broken. The site still earns more than it did three years ago. But the inventory the site now produces is a different product. The floor prices were set when 90% of traffic was US. The SSP list was assembled when the site had one content category. The ad density was tuned for article lengths the site no longer publishes. The formats were chosen for a device mix that has since shifted toward mobile.None of those decisions are wrong. They are simply old. And because they were never revisited, the site is monetising 2026 inventory through a 2023 lens.What "Outgrowing" Actually MeansThe phrase "advertising strategy" is often used to mean ad tech configuration: which SSPs, which formats, which floor prices. That is not a strategy. That is a snapshot of a set of assumptions about a business.A real advertising strategy makes assumptions about five things: who the audience is, where they are, how they arrive, what they consume, and what advertisers will pay to reach them. When a publisher grows, all five can change. Not incrementally. Structurally.The problem is that no part of the ad stack updates itself when those assumptions change. Floor prices stay where they were set. SSP lists stay where they were built. Ad density stays where it was calibrated. The strategy keeps serving a business that no longer exists, and the dashboard keeps reporting numbers that look normal because they are only being compared against a version of the same site that had the same problem.The Five Dimensions Where Growth Changes the RequirementGeography. A site that was 90% US and is now 60% US has a different demand profile. Tier-1 floor prices applied to tier-2 inventory reduce fill without raising CPM. A single SSP with strong US demand but weak European coverage will underperform on a third of the site's traffic. The inventory did not get worse. The demand stack stopped matching the inventory.Content architecture. Playwire's 2026 ecosystem analysis found that impressions per session (r=0.60) and impressions per pageview (r=0.57) are the two strongest predictors of revenue performance, outperforming fill rate, viewability, CPM, and session duration. That means the primary monetisation lever is not ad tech, it is content architecture. A publisher that moved from short news posts to long-form analysis changed its article length but may not have changed its ad density, its lazy-loading logic, or its in-content placement strategy. The format changed. The monetisation of the format did not.Traffic source composition. News Corp has reported that direct traffic is ten times more valuable to advertisers than social traffic and five times more valuable than search. That is not a small spread. A publisher whose traffic mix shifted from 70% search to a blend of search, email, and direct has quietly become a more valuable property. If CPMs did not move with that shift, the strategy failed to capture a real improvement in inventory quality.Device mix. Desktop and mobile have different demand, different viewability profiles, and different optimal ad density. A site that was desktop-dominant three years ago and is now mobile-dominant is selling a different product. Sticky units, in-page formats, and mobile-specific floor prices all behave differently. If the strategy was built for a desktop audience, the mobile growth is being under-monetised.Authenticated audience. The Reuters Institute reported that 79% of news publishers now rate first-party data strategy as a top three priority. That number reflects a real shift: publishers who built logged-in, subscribed, or email-connected audiences now hold an asset that commands a premium in the post-cookie market. If a publisher grew a 200,000-person newsletter and never changed its monetisation strategy to activate that audience, it is leaving the premium on the table.The Market Moved TooPublishers are not the only thing that changed. The market repriced.In Q2 2026, publisher ad request volumes fell between 32% and 37% year over year in the US and between 39% and 41% in the UK. Meanwhile, average eCPMs rose roughly 30% in the UK and about 7% in the US. Supply contracted. Prices rose. The publishers who captured that repricing were the ones whose floor strategy and demand mix adapted to it. Publishers whose floors were set during the abundant-supply era of 2023 were still filtering out bids that had become competitive.A similar pattern applies to density. Raptive's tests found that reducing ad density by approximately 16% produced CPM increases that offset or exceeded the loss of impressions. Freestar removed 50% of ad units on one site and saw revenue fall only 5%, while traffic from top sources rose 28% and revenue later surpassed pre-cleanup levels. Both experiments point to the same conclusion: the industry has repriced quality, and publishers who did not revisit their density assumptions did not benefit from it.A Diagnostic: Strategic Problem or Temporary Problem?Not every underperformance is a strategic mismatch. CPMs fluctuate. Seasonal demand shifts. A bad month happens. The diagnostic question is not "is revenue down?" It is "did something about the business change that the strategy has not responded to?"Work through the following. If two or more of these are true, the problem is strategic.Did your GEO mix shift by more than 10 percentage points in the last 24 months? If yes, your floor prices and SSP mix are probably wrong for part of your traffic.Did your average article length, page depth, or format mix change materially? If yes, your ad density and placement logic were calibrated for a version of your content that no longer exists.Did your traffic source composition shift toward direct, email, or authenticated visitors? If yes, your inventory became more valuable and your CPMs should have moved with it. If they did not, the strategy is not capturing the improvement.Did your device mix shift materially toward mobile? If yes, desktop-tuned formats and floor prices are underperforming on the majority of your traffic.Are you monetising your first-party audience the same way you did before you built it? If yes, you built an asset and did not activate it.If the answers cluster around "yes," the issue is not that the current network is underperforming. It is that the current strategy is answering questions the business stopped asking.Why Reassessing Is Not the Same as SwitchingThe instinct when publishers sense a monetisation problem is to evaluate other networks. That is often the wrong first step. Switching is an execution decision. Reassessing is a strategic one. Executing before diagnosing produces churn without improvement.A reassessment asks different questions. Does the current demand stack cover the geographies the site now serves? Do the floor prices reflect the current market and the current audience quality? Is the ad density calibrated for the content the site actually publishes? Are the formats matched to the device mix the site actually has? Is the authenticated audience being activated, or is it just being counted?Most publishers who run this exercise find that two or three assumptions are stale. Some can be corrected without changing partners at all. Others point to a genuine demand-side gap that the current network cannot close, either because it lacks coverage in a specific geography or because its format support does not match the inventory the site now produces.That distinction matters. It is the difference between a publisher who switches networks every eighteen months looking for a lift, and one who stays with a partner for years because the fit is still right.If a reassessment points to a specific demand-side gap where inventory that should attract premium buyers in a particular geography or format does not, that is the point where a partner conversation becomes useful rather than premature. Adstork works with established publishers whose inventory has moved beyond what their current demand stack was built to serve, often as a secondary source tested alongside what already works rather than as a replacement. You can request a review of your current setup here if you want a second opinion on where the gap actually sits.What This Means in PracticeMost publishers treat monetisation as a project. You set up the ads, you optimise them for a while, and then the setup becomes background infrastructure. The website keeps changing. The infrastructure does not.A more durable approach is to treat the advertising strategy the way a publisher treats editorial strategy: something that is reviewed on a cadence, not something that is set and forgotten. An annual review is enough for most publishers. A review triggered by any of the following is better:• A material shift in GEO mix• A material shift in device mix• The launch of a new content vertical or format• A meaningful increase in authenticated audience• A sustained change in the wider ad market, like the supply contraction the industry saw in early 2026The question to ask at each review is not "is our revenue growing?" It is "does our current setup still match the business we have become?" If the answer is no, the work is to identify which assumptions are stale, correct the ones that can be corrected internally, and test the ones that require a different partner.Growth is a good problem. But growth without a matching strategy is just a larger version of the same mismatch.Three Questions Publishers AskHow often should a publisher actually reassess its advertising strategy? Annually is the minimum. More often if the site has undergone a material change in geography, device mix, content format, or audience composition. The signal to look for is not a revenue decline. It is a divergence between how the business has changed and how the monetisation setup is configured.How do I tell if the problem is strategic or just market conditions? Market conditions affect everyone. Strategic problems affect you disproportionately. Compare your performance against publishers in your vertical and geography, not just against your own history. If your category peers are holding CPMs while you are not, the issue is probably internal. If everyone is declining, it is the market.Can I evolve my strategy without disrupting existing revenue? Yes. Most of the corrections (floor pricing, density calibration, format mix, placement logic) can be tested on segments of traffic without touching the whole site. Partner-level changes are the ones that require more care, and they should follow a controlled test rather than a full switch. The sequence that works is: diagnose first, correct what you can internally, then test external changes against a baseline you understand.
Read More
-
04 Sep, 2026
How Do Publishers Know When Their Current Ad Network Has Reached Its Limit?
Your traffic is growing. Your content is strong. But your ad revenue has flatlined. You've tweaked placements, tested formats, and adjusted floors—yet nothing moves the needle.This is the quiet signal that your current ad network may have reached its limit.The challenge is that revenue declines rarely look like a crisis in your dashboard. A 10% CPM compression over four weeks looks like normal market volatility. It gets attributed to seasonal slowdowns or advertiser budget cycles. The problem underneath goes unfound.This guide walks you through nine critical signals that indicate your ad network has reached its limit—and how to distinguish temporary noise from structural underperformance.Key TakeawaysRevenue plateaus despite traffic growth are the clearest sign your network has hit its ceiling.Declining eCPM without market explanation signals demand gaps or optimisation failures.Fill rate drops from 78% to 64% over weeks can look like normal variance—until it doesn't.Technical issues like misconfigured floors or unsynced auctions can silently drain revenue.The "honeymoon phase" after switching is temporary—judge performance only after 60 days of data.If your network hasn't adapted to AI-driven traffic shifts or cookie deprecation, it's falling behind.1. Revenue Has Plateaued Despite Traffic GrowthThis is the most obvious signal. Your traffic is increasing—but your ad revenue is flat or declining.When audience growth no longer translates to revenue growth, your monetisation is not scaling with your traffic. Your network may be struggling to attract incremental demand for your growing inventory, or it may be optimising for metrics that don't capture the full value of your audience.As one publisher noted, "Display CPMs are flatlining, and the buy side is consolidating around fewer, larger deals." If your network isn't accessing those premium deals, your revenue will stagnate even as your traffic grows.What to check: Compare your traffic growth rate against your revenue growth rate over the last 6-12 months. If the gap is widening, your network is not capturing value from your incremental audience.2. CPM and eCPM Are Declining Without Market ExplanationIf your eCPMs are falling while industry benchmarks remain stable, your current platform likely has demand gaps or optimisation issues that newer competitors have already solved.Programmatic revenue depends on the quality and accuracy of the signals your inventory sends to advertisers. When those signals degrade—because of misconfigured tags, broken audience segmentation, or outdated technology—your inventory looks less valuable than it actually is.The result: CPMs drop. Fill rates decline. And your revenue dashboard shows numbers that look normal because they are only slightly lower than last week, and slightly lower the week before that.What to check: Export 60-90 days of eCPM and CPM data. Compare against industry benchmarks. If your numbers are declining while benchmarks are stable, your network is underperforming.3. Fill Rate Is Dropping ConsistentlyEvery ad request that doesn't get filled is lost revenue. A fill rate decline from 78% to 64% over three weeks might look like normal programmatic variance—until it doesn't.Low fill rates create a vicious cycle: advertisers and ad networks use publisher fill rate data as a signal of inventory reliability. Publishers with consistently low fill rates may receive fewer competitive bids, further reducing both fill rate and eCPM.If traffic quality is questionable, DSPs and their partners may avoid bidding on that inventory. For a publisher with high traffic volume, poor quality will mean many unsold impressions.What to check: Track fill rate by geography, device, and format. If specific segments are underperforming, your network may lack demand in those areas.4. Bid Density Is DecliningBid density—the number of bids per auction—is a leading indicator of advertiser interest. When bid density drops, it means fewer buyers are competing for your inventory.Server-side header bidding can reduce browser-side latency, but in some cases, it can lead to lower bid density or CPMs. Lower match rates or lower signal quality can reduce buyer competition and put downward pressure on CPMs.When auctions are not synchronised properly, good bids never reach the final auction. A small technical detail, but a big impact on fill rate and auction pressure.What to check: Review your header bidding wrapper and Google Ad Manager alignment. If valid demand never reaches the final auction, fill rate drops and impressions go unserved.5. Technical Issues Are Going UnresolvedSimple configuration gaps can quietly cost publishers significant revenue. When ad networks fail to address technical issues, revenue leaks compound over time.Common technical issues include misconfigured floor prices that reduce fill rates, unsynchronised auctions that prevent good bids from reaching the final auction, and consent signal loss that reduces eligible demand.If your network isn't proactively identifying and fixing these issues, your revenue is silently leaking.What to check: Audit your ad stack configuration. Are floor prices optimised dynamically? Are your wrapper and ad server synchronised? Are you losing consent signals?6. Support Has Become UnresponsiveWhen your ad network's support team stops providing meaningful optimisation guidance, it's a signal that your account is no longer a priority.The best ad networks provide dedicated account management, proactive optimisation recommendations, and quick resolution of technical issues. If you're getting generic responses or no responses at all, your network has likely moved on to larger accounts.What to check: Review your support interactions over the last 3-6 months. Are you receiving proactive optimisation advice? Are technical issues resolved quickly? Do you have a dedicated account manager?7. The Network Hasn't Adapted to Industry ChangesThe advertising industry is evolving rapidly. In Q2 2026, publisher ad request volumes fell 32% to 37% year over year in the U.S. and 39% to 41% in the U.K. Publisher ad supply on the open web fell by up to 40%.If your network hasn't adapted to these changes—by embracing server-side header bidding, supporting new formats like CTV, or optimising for first-party data—it's falling behind.Networks that don't invest in AI-driven optimisation, transparent reporting, or diversified demand sources will struggle to maintain performance as the market shifts.What to check: Does your network support header bidding? Do they offer dynamic floor pricing? Are they investing in first-party data solutions? Have they adapted to cookie deprecation?8. The Honeymoon Phase Has Faded Without Sustained ImprovementWhen publishers switch ad networks, they often experience a significant RPM jump in week one, followed by a painful dip around day 30. This is the technical reality of how programmatic systems learn, sync, and recalibrate.Short-term spikes after switching are usually temporary, as DSPs, cookie syncing, and price floors need 30 to 60 days to settle into a true baseline.If your current network delivered an initial boost but performance has since stabilised below expectations, it may have reached its limit for your traffic profile.What to check: Judge a new stack only after 60 days of data. If performance hasn't improved beyond your previous network's baseline, the new network may not be a significant upgrade.9. Reporting Has Become OpaqueAd networks should provide dashboards accessible to every publisher to track performance in real time. This helps you analyze their performance and identify data discrepancies.If your network's reporting is opaque—lacking granular data by geography, device, format, and placement—you cannot optimise effectively. You're operating in the dark.The best networks provide transparent, real-time reporting that shows you exactly what is happening with your inventory. If yours doesn't, it's time to reconsider.What to check: Can you see fill rate, eCPM, and revenue by geography, device, and format? Can you export data for custom analysis? Do you have access to bid-level data?If you're seeing these signals, it may be time to evaluate whether your current network can still deliver for your growing business. Adstork provides transparent reporting, multiple demand sources, and dedicated support to help publishers scale their revenue. Explore Adstork's publisher solutions and see how a modern ad network can help you break through your revenue ceiling.Comparison Table: Healthy Network vs. Network at Its LimitA quick reference guide to distinguish a healthy ad network from one that has reached its limit.SignalHealthy NetworkNetwork at Its LimitRevenue vs. TrafficRevenue grows with trafficRevenue plateaus despite traffic growtheCPM TrendStable or growing vs. benchmarksDeclining without market explanationFill RateConsistent (80%+)Dropping consistentlyBid DensityMultiple competitive bidsDeclining competitionTechnical SupportProactive, responsive, knowledgeableUnresponsive, generic, slowIndustry AdaptationEmbracing new formats, AI, first-party dataStagnant, outdated technologyReportingTransparent, granular, real-timeOpaque, limited, delayedIndustry Insight: The Hidden Cost of Staying Too LongThe cost of staying with a network that has reached its limit is not always visible in your dashboard. It's a slow, silent drain on your revenue.At the scale of programmatic advertising, even a silent 10% compression in effective CPMs across a publisher's inventory translates to significant annual revenue loss. The problem is that a 10% CPM compression over four weeks rarely looks like a crisis in a dashboard.Many publishers also know that CPMs fluctuate, fill rates vary, and some revenue loss is just part of how the ecosystem works. What far fewer publishers know is how much of that lost revenue is not a market problem—it is a data or partner problem.One publisher noted that sales teams would sometimes overpromise on impression volume, leaving ops teams scrambling to deliver campaigns when the actual site traffic falls short. If your network is overpromising and underdelivering, it has reached its limit.What to Do Next: A 4-Step Action PlanIf you're seeing multiple signals that your network has reached its limit, here is a structured approach to evaluating your options.Step 1: Audit your current setup. Export 60-90 days of data from your existing dashboard. Include RPM by geography, fill rate, eCPM, and revenue per session.Step 2: Identify the gaps. Compare your performance against industry benchmarks. Where are you underperforming? Is it fill rate in certain geos? eCPM on mobile? Support responsiveness?Step 3: Test alternatives. Partition a portion of traffic towards new ad configurations before switching your site over wholesale. Run a controlled test with a new network on a limited segment.Step 4: Evaluate after 60 days. Short-term spikes after switching are temporary. Judge a new stack only after 60 days of data. Compare effective RPM, fill rate, and revenue per session—not just headline CPM.Your ad network has a limit. The question is whether you've reached it—and whether you'll recognise the signals before revenue loss compounds.The nine signals in this guide—revenue plateaus, declining eCPM, dropping fill rates, weakening bid density, unresolved technical issues, unresponsive support, failure to adapt, faded honeymoon phases, and opaque reporting—are your early warning system.If you're seeing multiple signals, it's time to evaluate your options. The cost of staying too long is not always visible in your dashboard—but it's real.Adstork helps publishers break through revenue ceilings with transparent reporting, multiple premium demand sources, and dedicated support. Sign up for a free Adstork publisher account and see what a modern ad network can do for your revenue.Your immediate action plan: Audit your current performance against the nine signals. Identify your biggest gaps. Research 2-3 alternative networks that address those gaps. Run a controlled test on a limited segment. Evaluate after 60 days. Make a data-driven decision.FAQsHow do I know if my ad network has reached its limit? Look for nine signals: revenue plateaus despite traffic growth, declining eCPM without market explanation, dropping fill rates, weakening bid density, unresolved technical issues, unresponsive support, failure to adapt to industry changes, faded honeymoon phase without sustained improvement, and opaque reporting.What is a normal eCPM fluctuation vs. a sign of network failure? A 10% CPM compression over four weeks rarely looks like a crisis in a dashboard. If your eCPMs are declining while industry benchmarks are stable, your network likely has demand gaps or optimisation issues.How long should I wait before switching ad networks? If you've recently switched, judge performance only after 60 days of data. If you've been with a network for over a year and are seeing multiple decline signals, start evaluating alternatives immediately.Should I switch networks entirely or add a second one? Many successful publishers use multiple networks in a header bidding setup. Adding a network can introduce competition without disrupting existing revenue. Test before you switch.What metrics should I track to monitor network performance? Track revenue per session, fill rate by geography and device, eCPM, bid density, and viewability. Don't rely on headline CPM alone—it can be misleading.Can technical issues make a network look like it's underperforming? Yes. Simple configuration gaps can quietly cost publishers significant revenue. Misconfigured floor prices, unsynchronised auctions, and consent signal loss can all reduce fill rates and eCPM.
Read More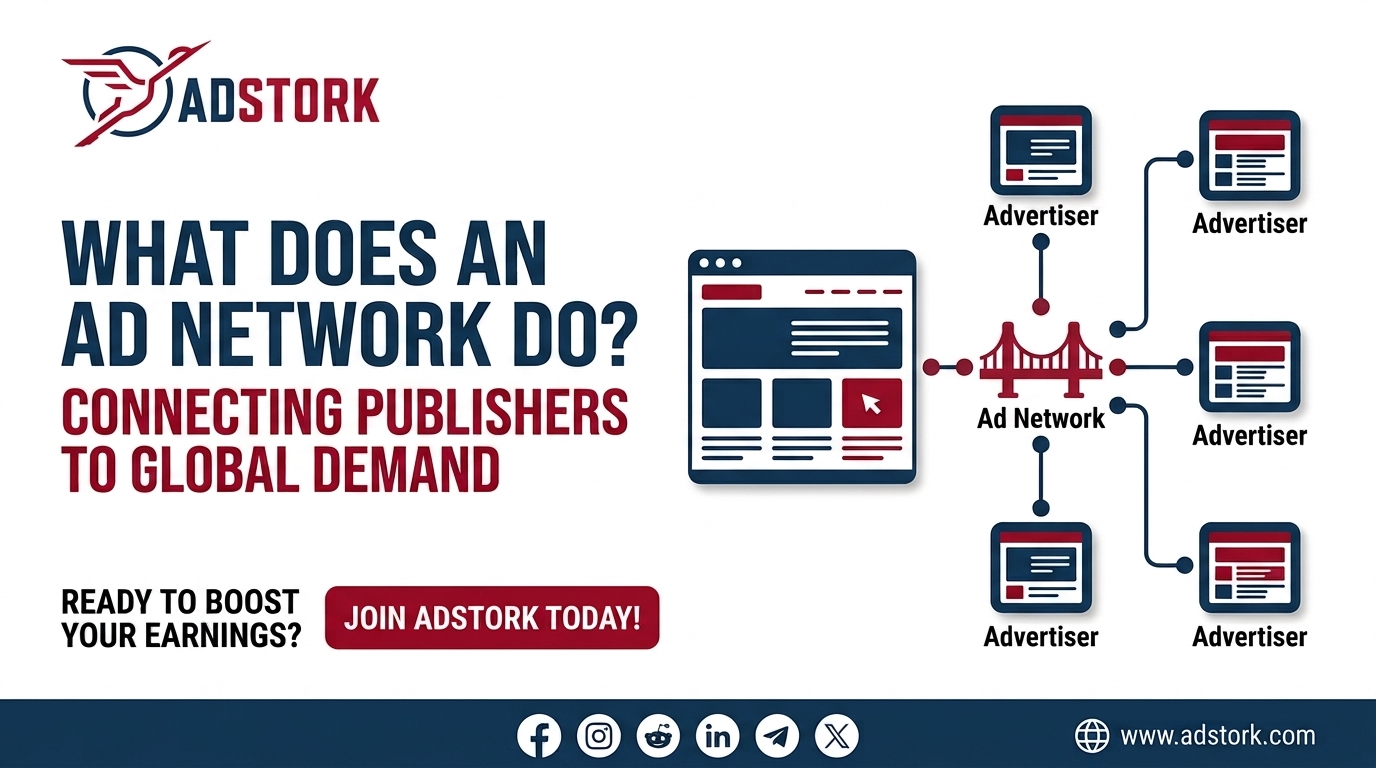
-
01 Sep, 2026
What Does an Ad Network Actually Do for a Publisher?
You have heard the term "ad network." You know it has something to do with making money from your website. But what does it actually do?Think of an ad network as the bridge between two worlds: publishers who have ad space to sell and advertisers who want to buy it. Without an ad network, you would need to find advertisers yourself, negotiate prices individually, handle the technical delivery of ads, and chase payments—all while trying to run your website.An ad network handles all of that for you. It takes your empty ad space, fills it with paying ads, and sends you revenue. Everything else—technology, relationships, reporting, payments; happens behind the scenes so you can focus on creating content and growing your audience.This guide walks you through exactly what an ad network does, step by step, from the moment a user visits your site to the moment you receive your payout.Key TakeawaysAn ad network is the intermediary that connects publishers with advertisers.It handles everything: filling ad space, running auctions, delivering ads, tracking performance, and paying you.The process follows a clear path: ad request → auction → ad delivery → reporting → revenue.Ad networks save you from finding advertisers, negotiating prices, and chasing payments.The right ad network provides technology, demand, transparency, and support—all in one platform.The Ad Network Journey: Step by StepThe journey from a user visiting your site to you earning revenue follows a clear, logical path. Here is exactly what happens.1. Your Website Sends an Ad RequestWhen a user visits your website, your ad code (provided by the ad network) sends an ad request to the network's servers. This request contains information about the user and the page.The request includes contextual signals—the page topic, keywords, and content category. Geographic data shows the user's location. Device information identifies whether they are on desktop, mobile, or tablet. User behavior signals may include engagement patterns and return frequency.This request happens in milliseconds. The user does not see it. They only see the ad that eventually loads.2. The Ad Network Connects to Advertiser DemandThe ad network takes your request and sends it to multiple advertisers, demand sources, and exchanges simultaneously. This is where the network's relationships matter.Ad networks with strong demand sources premium SSPs, direct advertisers, and programmatic exchanges can connect your inventory to the right buyers. Networks with weak demand sources will struggle to fill your inventory at good prices.The goal is to expose your inventory to as many potential buyers as possible. More buyers mean more competition, which means higher CPMs.3. The Auction or Matching Process BeginsThis is where the magic happens. The ad network runs an auction where multiple advertisers bid on your inventory in real time.Each advertiser evaluates the request based on their campaign goals. Do they want to reach users in this geographic location? Is the content context relevant to their brand? Is the user likely to engage?Advertisers submit bids based on the value they assign to the impression. The highest bid wins—assuming it meets your floor price. This is called real-time bidding (RTB), and it happens in milliseconds.Some networks use header bidding, where multiple demand sources bid simultaneously. Others use a waterfall, where partners are called in a fixed order. Header bidding typically generates higher CPMs because more competition drives prices up.4. The Creative Is DeliveredOnce the winning bid is selected, the ad network delivers the ad creative to your website. The user sees the ad in the designated space on your page.The ad creative might be a display banner, a native ad, a video, a popunder, or a push notification. The format determines how the ad is rendered and how users interact with it.This is the only part of the process the user sees—the ad itself. Everything else happens behind the scenes.Neuromarketing insight: users are unaware of the auction. They simply see an ad that feels relevant to their context. This relevance reduces cognitive resistance and increases engagement. The ad network's ability to match the right ad to the right user in real time is what makes programmatic advertising effective.5. Performance Is TrackedThe ad network tracks every impression, click, and conversion. This data is recorded in real time and made available to you through the network's reporting dashboard.Key metrics include impressions (how many times ads were displayed), clicks (how many times users clicked), CTR (click-through rate), CPM (cost per mille), eCPM (effective CPM), fill rate (percentage of requests filled), and revenue (total earnings).Transparent reporting is essential for optimisation. Without it, you cannot know what is working and what is not. The best ad networks provide granular data segmented by country, device, format, and placement.6. You Review Your EarningsYour earnings dashboard shows your revenue in real time. You can see how much you have earned today, this week, and this month.The dashboard also shows which formats, geos, and placements are performing best. This data helps you optimize your monetization strategy.Most ad networks provide regular payment cycles, typically monthly or weekly. You receive your earnings based on the network's payment terms and your selected payment method.What a Good Ad Network ProvidesNot all ad networks are created equal. A good ad network provides more than just ad tags. Here is what to look for.Demand access. Premium demand sources that pay well and fill consistently. Direct advertiser relationships and programmatic exchanges. Global coverage that matches your traffic profile.Ad technology. Real-time bidding and header bidding capabilities. Multiple ad formats including display, native, video, and popunder. Ad quality controls and brand safety features. Fraud prevention and invalid traffic filtering.Transparency. Granular reporting segmented by country, device, format, and placement. Real-time data access. Clear payment terms and fee disclosure. No hidden charges.Support. Dedicated account management. Responsive support team. Optimisation guidance. Technical assistance for integration.Payment reliability. Consistent payment cycles. Multiple payment options. Low minimum payout thresholds. No payment delays.Industry Insight: The Value Ad Networks ProvideAd networks have evolved significantly. Modern networks provide value far beyond basic ad serving.AI-powered optimisation is becoming standard. Networks use machine learning to optimise floor prices, demand routing, and ad placement in real time.Multi-format support is essential. Publishers want one network that can handle display, native, video, and popunder formats. Managing multiple networks for different formats is inefficient.Global demand is increasingly important. Ad networks with strong international demand help publishers monetise traffic from all regions.Transparency is now expected. Publishers demand to know where their revenue comes from, who is buying their inventory, and what fees are being applied.The network that provides the best combination of demand, technology, transparency, and support will earn long-term publisher loyalty.At its core, an ad network handles the technology, demand, and payments so you can focus on what matters—creating content and growing your audience. Adstork provides all of this with instant approval, global demand, transparent reporting, and dedicated support. Sign up for a free Adstork publisher account and see how easy monetisation can be.Comparison Table: Ad Network vs. No Ad NetworkHere is what your monetisation experience looks like with and without an ad network.ActivityWithout an Ad NetworkWith an Ad NetworkFinding AdvertisersYou need to find and negotiate with each advertiser individuallyNetwork connects you to hundreds of advertisers automaticallyPricingFixed rates, limited competitionReal-time auctions, competitive bidsAd DeliveryYou need to host and serve ads yourselfNetwork handles delivery and renderingReportingManual tracking, or none at allAutomated, real-time dashboardsPayment CollectionYou chase payments from each advertiserNetwork collects and pays youTime InvestmentSignificant—sales, negotiation, technicalMinimal—focus on contentOptimisationLimited data, manual adjustmentsAI-powered, data-drivenFuture Outlook: The Evolving Role of Ad NetworksThe role of ad networks is evolving. Several trends are reshaping what publishers should expect from their networks.AI and automation are becoming standard. Networks increasingly use machine learning to optimise yield, detect fraud, and improve ad targeting. Publishers benefit from higher performance without manual effort.First-party data integration is growing. Networks that help publishers collect and activate first-party data will provide more value in the post-cookie era.Transparency requirements are increasing. Publishers demand visibility into demand sources, fees, and auction dynamics. Networks that resist transparency will lose publishers.Multi-format support is becoming standard. Publishers want one partner that can handle all formats—not separate networks for display, native, and video.The future belongs to ad networks that provide comprehensive solutions—technology, demand, transparency, and support—in a single, easy-to-use platform.An ad network is the bridge between your website and advertisers. It handles everything from filling your ad space to running auctions, delivering ads, tracking performance, and paying you.Without an ad network, you would need to find advertisers yourself, negotiate prices individually, handle technical delivery, and chase payments. With an ad network, you focus on creating content and growing your audience—the network handles the rest.Adstork provides everything a publisher needs: instant approval, global demand, multiple formats, transparent reporting, and dedicated support. All in one platform. Sign up for a free Adstork publisher account and see what a modern ad network can do for you.FAQsWhat does an ad network do for a publisher? An ad network connects your website's ad inventory to advertisers, runs real-time auctions to determine the highest bid, delivers the ad to your user, tracks performance, and handles payments. It does everything so you do not have to find advertisers or manage ad delivery yourself.How do ad networks make money? Ad networks typically take a percentage of the ad revenue as a fee. The exact percentage varies by network. Some networks also charge advertisers a markup on media purchases. Transparent networks disclose their fee structure clearly.Do I need an ad network to make money from ads? You could theoretically find advertisers directly and sell ad space yourself. But this requires significant time and effort—finding advertisers, negotiating prices, managing ad delivery, and chasing payments. Most publishers use ad networks because they handle everything efficiently.What is the difference between an ad network and a DSP? An ad network connects publishers with demand sources. A DSP (demand-side platform) is used by advertisers to buy inventory across multiple networks and exchanges. Publishers work with ad networks; advertisers work with DSPs.What is real-time bidding? Real-time bidding (RTB) is the process where advertisers bid on each impression in milliseconds. When a user visits your site, an auction occurs, and the highest bidder's ad is delivered. RTB ensures you capture the true market value of your inventory.How do I choose an ad network? Evaluate networks based on approval speed, traffic requirements, supported formats, GEO coverage, demand quality, reporting transparency, payment terms, support quality, and account management. Use the Publisher's Checklist to compare your options.
Read More